Professional football is slow-motion suicide.
Previous coverage here and here.
Thursday, January 10, 2013

Wednesday, January 9, 2013
Score one against corporations being people.
Taking a break from our platinum coin coverage, let's see what's the latest in the fight over corporate personhood. The San Francisco Chronicle has a story about a case that decided whether corporations are people for purposes of counting the number of occupants in a car.
Tuesday, January 8, 2013
The Importance of Interpretation
This is part three in my planned 94-part series on the $1 Trillion Platinum Coin, which clever people continue to peddle feverishly and foolishly.
The basic argument in favor of the legality of the Platinum Coin is, "Hey, the statute says what it says. Sure, it's a stupid loophole, but we take the law as we find it." In other words, it's hyper-technical literalism—strict constructionism—a way of interpreting texts that even Justice Scalia denounces.
But it's also self-defeating because if you give a hyper-literal reading to the relevant statute (31 U.S.C. 5112) you'll see that it is self-contradictory. That is, it contains irreconcilable provisions.
Section 5112(a) says: "The Secretary of the Treasury may mint and issue only the following coins" and then goes on to specify just twelve specific coins of specific denomination. By its terms, § 5112(a) prohibits the minting of any other coins. Since the trillion dollar platinum coin is not among the enumerated coins, the Secretary of the Treasury may not mint or issue it. "Hey, just read the statute, idiot!"
But wait! Section 5112(k) says "The Secretary may mint and issue platinum bullion coins and proof platinum coins." So, under subsection (k), the Secretary can mint a coin that subsection (a) clearly prohibits. DOES NOT COMPUTE!
Even worse, there is the embarrassment of § 5112(e), which authorizes the minting of silver dollars. That provision, however, is reconcilable with subsection (a) because it explicitly begins with a magical phrase: "Notwithstanding any other provision of law, the Secretary shall mint and issue . . . [silver dollars]." Subsection (k), the platinum-coin section, lacks the magic words. It just contradicts without excuse.
The provisions are irreconcilable—what Congress literally gives with subsection (k), it literally takes away with subsection (a). What can we do???
Well, we interpret the statute as a whole, of course. Turns out, there's a basic canon of interpretation that governs when two parts of statute are irreconcilable: the general/specific canon. This is the interpretive rule that, if two provisions are irreconcilable, the specific provision wins out over the more general provision. So if the question is whether the Secretary of Treasury may mint a platinum coin, you have two applicable provisions: (1) the general provision that the Secretary may mint only 12 kinds of coins, none of which are platinum; and (2) the specific provision that says the Secretary may indeed mint a platinum coin. The rule is that the specific provision wins. THE PLATINUM COIN LIVES!
Now, this may seem like common sense. And it is. But remember: people are talking about the minting of a trillion dollar coin. So I am going back to first principles. Today's lesson: to give a statute its fair meaning, you have to read all of it, and you almost always have to interpret it. If you read just ten or twenty words and apply no judgment, you'll almost never actually know what the law is.
Keeping those basic concepts in mind, ask yourself a question: given that the specified denominations in § 5112 range from one cent to $50, does a fair reading of subsection (k) give the Secretary of Treasury "discretion" to mint and issue $1 trillion coins? Or would that be an abuse of the discretion delegated by Congress?
The basic argument in favor of the legality of the Platinum Coin is, "Hey, the statute says what it says. Sure, it's a stupid loophole, but we take the law as we find it." In other words, it's hyper-technical literalism—strict constructionism—a way of interpreting texts that even Justice Scalia denounces.
But it's also self-defeating because if you give a hyper-literal reading to the relevant statute (31 U.S.C. 5112) you'll see that it is self-contradictory. That is, it contains irreconcilable provisions.
Section 5112(a) says: "The Secretary of the Treasury may mint and issue only the following coins" and then goes on to specify just twelve specific coins of specific denomination. By its terms, § 5112(a) prohibits the minting of any other coins. Since the trillion dollar platinum coin is not among the enumerated coins, the Secretary of the Treasury may not mint or issue it. "Hey, just read the statute, idiot!"
But wait! Section 5112(k) says "The Secretary may mint and issue platinum bullion coins and proof platinum coins." So, under subsection (k), the Secretary can mint a coin that subsection (a) clearly prohibits. DOES NOT COMPUTE!
Even worse, there is the embarrassment of § 5112(e), which authorizes the minting of silver dollars. That provision, however, is reconcilable with subsection (a) because it explicitly begins with a magical phrase: "Notwithstanding any other provision of law, the Secretary shall mint and issue . . . [silver dollars]." Subsection (k), the platinum-coin section, lacks the magic words. It just contradicts without excuse.
The provisions are irreconcilable—what Congress literally gives with subsection (k), it literally takes away with subsection (a). What can we do???
Well, we interpret the statute as a whole, of course. Turns out, there's a basic canon of interpretation that governs when two parts of statute are irreconcilable: the general/specific canon. This is the interpretive rule that, if two provisions are irreconcilable, the specific provision wins out over the more general provision. So if the question is whether the Secretary of Treasury may mint a platinum coin, you have two applicable provisions: (1) the general provision that the Secretary may mint only 12 kinds of coins, none of which are platinum; and (2) the specific provision that says the Secretary may indeed mint a platinum coin. The rule is that the specific provision wins. THE PLATINUM COIN LIVES!
Now, this may seem like common sense. And it is. But remember: people are talking about the minting of a trillion dollar coin. So I am going back to first principles. Today's lesson: to give a statute its fair meaning, you have to read all of it, and you almost always have to interpret it. If you read just ten or twenty words and apply no judgment, you'll almost never actually know what the law is.
Keeping those basic concepts in mind, ask yourself a question: given that the specified denominations in § 5112 range from one cent to $50, does a fair reading of subsection (k) give the Secretary of Treasury "discretion" to mint and issue $1 trillion coins? Or would that be an abuse of the discretion delegated by Congress?
"A clever little scheme having only the color of legality..."
"...cannot be upheld."
Anyone who thinks the "platinum coin" solution to the Debt Ceiling is obviously legal needs to read Bloomington Nat'l Bank v. Telfer, 916 F.2d 1305 (7th Cir. 1990), in which a court bench-slapped the Comptroller of the Currency for abusing his discretion under the National Banking Act. Chevron deference goes only so far.
Anyone who thinks the "platinum coin" solution to the Debt Ceiling is obviously legal needs to read Bloomington Nat'l Bank v. Telfer, 916 F.2d 1305 (7th Cir. 1990), in which a court bench-slapped the Comptroller of the Currency for abusing his discretion under the National Banking Act. Chevron deference goes only so far.
Monday, January 7, 2013
The cost of incivility
While it depends somewhat on the case, normally I try to keep briefs I write free of invective or pejoratives. Mostly, that is because I figure that calling something "an outrage" (to use one phrase that lawyers seem to love) is ridiculous in a civil case. The Holocaust was an outrage. Darfur an outrage. Failure to perform the terms of a contract is not, and never will be, an outrage. The failure to turn over some piece of discoverable information is wrong and should not be countenanced by a court. But, it is not an outrage.
Saturday, January 5, 2013
Lance Armstrong's Lawyer
Juliet Macur of the New York Times reports that Lance Armstrong may confess to doping during his cycling career. (We previously discussed Mr. Armstrong here.)
I can't say I really care that much whether Armstong admits the doping or not. But I was intrigued by some comments that Tim Herman, Armstrong's lawyer, made to the New York Times about whether Armstong might confess: "I suppose anything is possible. Right now, that’s not really on the table."
I thought this was a strange comment. "Right now" that's not on the table? "Anything's possible"? This sort of implies that it is a possibility that could be on the table in the future. And it's far from the stern denial you might expect. Fundamentally, why would the lawyer say anything, especially on the record?
But you'll notice that the link I provided for Mr. Herman's comment isn't actually to the New York Times article itself. That's because that quote no longer appears in the New York Times article. Instead, the article now quotes Herman as saying, "Lance has to speak for himself on that." Good answer.
I suspect that Mr. Herman claims that this comment was made off the record and demanded that the quote be removed. Either that or he claims he was misquoted. I've sent an inquiry to Ms. Macur, the reporter, through Twitter but she has not responded. (Apparently she does not know the power I wield through this blog.)
I don't understand why lawyers ever talk to reporters about live cases. Nothing good can come of it. But I certainly like Mr. Herman's new quote better than his old one.
I can't say I really care that much whether Armstong admits the doping or not. But I was intrigued by some comments that Tim Herman, Armstrong's lawyer, made to the New York Times about whether Armstong might confess: "I suppose anything is possible. Right now, that’s not really on the table."
I thought this was a strange comment. "Right now" that's not on the table? "Anything's possible"? This sort of implies that it is a possibility that could be on the table in the future. And it's far from the stern denial you might expect. Fundamentally, why would the lawyer say anything, especially on the record?
But you'll notice that the link I provided for Mr. Herman's comment isn't actually to the New York Times article itself. That's because that quote no longer appears in the New York Times article. Instead, the article now quotes Herman as saying, "Lance has to speak for himself on that." Good answer.
I suspect that Mr. Herman claims that this comment was made off the record and demanded that the quote be removed. Either that or he claims he was misquoted. I've sent an inquiry to Ms. Macur, the reporter, through Twitter but she has not responded. (Apparently she does not know the power I wield through this blog.)
I don't understand why lawyers ever talk to reporters about live cases. Nothing good can come of it. But I certainly like Mr. Herman's new quote better than his old one.
Neil Macdonald is not a member of the National Rifle Association.
At least I assume he is not a member based on this op-ed he wrote. He probably should be a member, however. Members of the NRA vote to elect the leadership of the NRA. So if you do not like the NRA's position on the availability of assault weapons or on the advisability of having an armed guard in every school, join the NRA and vote for leadership that does not espouse those positions. The alternative is joining anti-gun groups like the Brady Campaign to Prevent Gun Violence. I hope I do not insult anyone associated with the Brady Campaign by pointing out that the NRA has been cleaining the Brady Campaign's clock lately when it comes to both gun legislation and court decisions.
What do you think Mr. Torvik? Would infiltration be a more effective means of change than joining the current anti-gun groups?
What do you think Mr. Torvik? Would infiltration be a more effective means of change than joining the current anti-gun groups?
Friday, January 4, 2013
The Platinum Coin is a Terrible Idea
Now that we've averted the Fiscal Cliff, the country's next looming catastrophe is the "Debt Ceiling." This is the law that limits the amount the federal government can borrow. In about two months, we will hit the ceiling unless Congress acts to raise it, in which case the President will have to stop paying people the government owes money to. This would be calamitous. Republicans says they will demand spending cuts in exchange for any rise in the Debt Ceiling; Obama says he won't negotiate on this issue, because Congress needs simply to grant him the ministerial authority to create the debt necessary to pay for the spending that Congress has already appropriated.
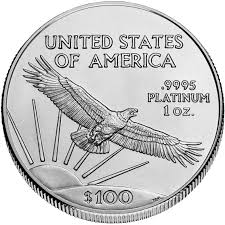 One clever idea that's been going around is that the President can short-circuit this whole crisis by having the Secretary of the Treasury order the minting a platinum coin with a $1 trillion face value. That coin could then be deposited with the Federal Reserve, which would credit the Treasury's account with the $1 trillion, which the President could use to pay the country's creditors.
This method of using coinage to raise revenue is called coin seigniorage. The Treasury's ability to mint coins is generally circumscribed by the fact that only certain denominations and types of coin are allowed. Specifically, 31 U.S.C. 5112 states:
This method of using coinage to raise revenue is called coin seigniorage. The Treasury's ability to mint coins is generally circumscribed by the fact that only certain denominations and types of coin are allowed. Specifically, 31 U.S.C. 5112 states:
Citzens United and freedom from Obamacare
One thing that some lawyers like to do is to wreck the weekend of their adversary. For example, a lot of lawyers like to serve motion papers late in the day on a Friday. This is particularly true of expedited motions, like one for a temporary restraining order, that do not follow longer briefing schedules. Apparently the desire to drop bombs on a Friday does not go away when one becomes a judge.
Tuesday, January 1, 2013
New year, new taxes, and an exercise in statutory interpretation
The Senate has passed a bill to avert / delay the so-called Fiscal Cliff. The bill's main feature is to make "permanent" most of President Bush's 2001 tax cuts, except that it creates a new 39.6% tax bracket starting at $400,000 for individuals and $450,000 for married couples filing jointly.
This morning I read a report that the bill included a radical provision that would impose a uniform (rather than marginal) tax rate of 35% on all the income of high-earners:
Mat 12564
The relevant provisions start at the bottom of page 6 of the document (line 22, specifically) where the 35% bracket is defined. It says:
To cut to the chase, the bill says that for each of these classes of filers, the tax rate shall be 35% for the income between the dollar amount at which "the highest rate bracket" begins and the dollar amount defined as "the applicable threshold." To understand this, let's look at at 26 U.S.C. § 1(a) as currently drafted:
Simple!
In conclusion, the economist Mr. Malpass seems to be mistaken.
This morning I read a report that the bill included a radical provision that would impose a uniform (rather than marginal) tax rate of 35% on all the income of high-earners:
Finally, rather than (or in addition to) simply slapping the old Clinton 39.6% top tax rate on incomes above $450,000 for joint filers, the economist David Malpass of Encima Global reports that "For incomes above $450,000, the bill also appears to take away the lower tax brackets, applying a 35% rate to all income up through $450,000." New Yorkers know this as a "benefits recapture" provision, and if Mr. Malpass is correct that it's there, it's not pretty.There was no link to Mr. Malpass's report or how he came to this conclusion, so I went to the text of the bill itself, which I've embedded here for your reading pleasure:
Mat 12564
The relevant provisions start at the bottom of page 6 of the document (line 22, specifically) where the 35% bracket is defined. It says:
(i) the rate of tax under subsections (a), (b), (c), and (d) on a taxpayer's taxable income in the highest rate bracket shall be 35 percent to the extent such income does not exceed an amount equal to the excess of—(I) the applicable threshold, over (II) the dollar amount at which such bracket begins, and
(ii) the 39.6 percent rate of tax under such subsections shall apply only to the taxpayer's taxable income in such bracket in excess of the amount to which clause (i) applies.Let's break this down. First, clause (i) applies to the rate of tax in the "highest rate bracket" under "subsections (a), (b), (c), and (d)." To what does this refer? It's not super clear, but in fact this is a reference to subsections (a)-(d) of 26 U.S.C. §1. These subsections define, respectively, the different tax brackets for: (a) married individuals filing joint returns; (b) head of household filers; (c) unmarried individual filers; and (d) married individuals filing separately.
To cut to the chase, the bill says that for each of these classes of filers, the tax rate shall be 35% for the income between the dollar amount at which "the highest rate bracket" begins and the dollar amount defined as "the applicable threshold." To understand this, let's look at at 26 U.S.C. § 1(a) as currently drafted:
For married couples filing jointly, the "applicable threshold" is $450,000 (see page 8, lines 1-2 in text above). Under 26 U.S.C. §1(a), the "highest rate bracket" begins at $250,000. Thus, the 35% rate bracket applies to income above $250,000 (that is "income in the highest rate bracket") as long as it does not exceed "the applicable threshold" ($450,000) minus "the dollar amount at which [the highest rate bracket] begins" ($250,000). In other words, a 35% tax applies to the $200,000 in income earned between $250,000 and $450,000. Then the 39.6% bracket applies to income above $450,000 under clause (ii).
If taxable income is: The tax is: Not over $36,900 15% of taxable income. Over $36,900 but not over $89,150 $5,535, plus 28% of the excess over $36,900. Over $89,150 but not over $140,000 $20,165, plus 31% of the excess over $89,150. Over $140,000 but not over $250,000 $35,928.50, plus 36% of the excess over $140,000. Over $250,000 $75,528.50, plus 39.6% of the excess over $250,000.
Simple!
In conclusion, the economist Mr. Malpass seems to be mistaken.
Subscribe to:
Posts (Atom)